Unsuitable investments occur when a broker or financial advisor recommends securities that do not align with an investor’s financial situation, investment objectives, or risk tolerance. These recommendations can expose investors to unnecessary risk and significant financial losses. That’s where an unsuitable investment lawyer may be able to provide help.
Help for Investors
If you suffered losses due to unsuitable investment recommendations, you may have the right to pursue recovery through FINRA arbitration.
Do You Have a Claim for Unsuitable Investments?
You may have a claim if your broker:
- Recommended high-risk investments despite conservative goals
- Failed to consider your financial situation or risk tolerance
- Overconcentrated your portfolio in a single investment or sector
- Recommended illiquid or complex investments without proper explanation
- Engaged in excessive trading (churning)
Even if an investment initially appeared suitable, it may still be considered unsuitable if it was inconsistent with your overall financial profile.
What Is the FINRA Suitability Rule?
FINRA Rule 2111 requires brokers to recommend investments that are appropriate based on an investor’s financial profile, including their objectives, risk tolerance, and financial circumstances.
For a full explanation of the rule and broker obligations, visit our FINRA Rule 2111 Suitability Explained page.
Common Examples of Unsuitable Investment Recommendations
The following situations may indicate that a broker recommended unsuitable investments:
High-Risk Investments for Conservative Investors
If a broker recommends speculative investments to a conservative investor seeking stability, the recommendation may violate FINRA suitability rules. Contact an unsuitable investment lawyer if your investments seem riskier than you want.
Lack of Diversification
Placing a large portion of a client’s portfolio into a single security or narrow sector can expose investors to significant risk.
Illiquid Investments
Investments with limited liquidity, such as private placements or non-traded real estate investment trusts, may be unsuitable for investors who require access to their funds.
Complex Investment Products
Structured products, derivatives, or alternative investments may carry risks that some investors may not fully understand. Investors asking themselves, “What is the FINRA suitability rule?” should understand that suitability can depend heavily on their individual financial circumstances.
Excessive Trading (Churning)
Churning or frequent trading in an account primarily to generate commissions may violate suitability rules and harm investor returns.
How to Prove a Suitability Violation
To establish a claim, investors typically must show:
- The broker made a recommendation
- The recommendation was unsuitable based on the investor’s profile
- The investor suffered financial losses
- The broker or firm failed to act in the investor’s best interest
Documentation such as account statements, new account forms, and communications with your advisor may be used as evidence. Evidence can also help establish whether a recommendation failed to meet obligations under FINRA Rule 2111.
Recovering Losses Through FINRA Arbitration
Most disputes between investors and brokerage firms are resolved through FINRA arbitration.
This process allows investors to seek compensation for losses caused by broker misconduct, including unsuitable investment recommendations. The FINRA suitability rule is relevant in arbitration when the dispute centers on whether a recommendation matched the investor’s financial profile.
The process typically involves:
- Filing a Statement of Claim
- Exchanging evidence (discovery)
- Attending a hearing before arbitrators
- Receiving a binding arbitration award
Why Work With an Unsuitable Investment Lawyer?
An experienced securities attorney can:
- Evaluate whether your broker violated suitability obligations
- Gather and analyze evidence
- Calculate damages
- Represent you throughout the arbitration process
Contact an Unsuitable Investment Lawyer
If you believe a broker recommended unsuitable investments that resulted in financial losses, the attorneys at The White Law Group may be able to help.
Our securities fraud attorneys represent investors nationwide in claims against brokerage firms involving many types of investment fraud.
If you believe you have suffered losses due to unsuitable investments, contact our team of unsuitable investment lawyers for a free consultation at (888) 637-5510.
Unsuitable investments refer to financial products unsuitable for your investment goals, risk tolerance, or financial situation. Brokers or financial advisors typically recommend or sell these investments, and they may not have adequately assessed your individual needs or provided appropriate advice.
The Financial Industry Regulatory Authority (FINRA) is the self–regulator that oversees brokers and brokerage firms. FINRA has rules regarding inappropriate investments. If your broker fails to follow FINRA rules, you may want to seek legal advice from an experienced, unsuitable investment lawyer.
FINRA Rule 2111 requires a firm or its representative to have a reasonable basis for believing that a recommended transaction or investment strategy involving a security is suitable for the customer. This basis is based on the information obtained through the firm’s or associated person’s reasonable diligence in understanding the customer’s investment profile.
The rule states that the customer’s investment profile “includes, but is not limited to, the customer’s age, other investments, financial situation and needs, tax status, investment objectives, investment experience, investment time horizon, liquidity needs and risk tolerance,” among other information. Unsuitable investment lawyers examine each factor when assessing the strength of an unsuitable investment case.
According to FINRA Rule 2111, brokers must have a firm understanding of both the product and the customer. A lack of such understanding violates the suitability rule.
Firms that fail to perform adequate due diligence or make unsuitable recommendations can be held responsible for losses in a Financial Industry Regulatory Authority (FINRA) arbitration claim.
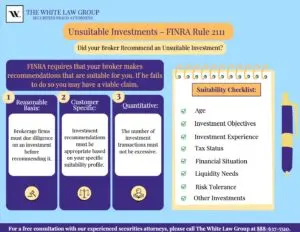
Rule 2111 describes three separate suitability obligations that unsuitable investment lawyers typically investigate when building a case:
- (1) Reasonable Basis – firms must have a reasonable basis to believe, based on adequate due diligence, that a recommendation is suitable, at least for some investors. The broker must know the risks associated with the security or investment strategy. Since most investment opportunities are suitable for at least some investors, firms need to understand the potential risks of the investment.
- (2) Customer-specific: Firms must have reasonable grounds to believe a recommendation suits the investor, including investment experience, retirement goals, investment time horizon, liquidity needs, risk tolerance, and financial situation. Unsuitable investment lawyers often focus on this obligation when attempting to prove a broker pushed an unsuitable investment on their client.
- (3) Quantitative: Firms must have a reasonable basis for believing that the number of recommended transactions within a certain period is not excessive (i.e., that the investor’s account is not being churned).
Do I need an Unsuitable Investment Lawyer?
The following are situations involving unsuitable investment recommendations by a broker or financial advisor. If you feel any of them apply to you, you should contact an unsuitable investment lawyer.
- High-risk investments for conservative investors: If you have a low-risk tolerance and are looking for stable and secure investments, your broker should not recommend high-risk investments such as speculative stocks, options trading, or highly leveraged products. These investments carry a significant risk of loss and may not align with your investment objectives.
- Lack of diversification: You must diversify to decrease your risk. If your broker sold you a prominent position in a single stock or a few closely related securities without considering diversification, it could be regarded as an unsuitable investment and potentially grounds for you to contact an unsuitable investment lawyer. Concentrated positions can expose you to volatility and potential losses if the value of your investment declines.
- Illiquid investments with limited access to funds: Illiquid investments, such as private placements or non-traded REITs, lack readily available markets to sell or exit the investment. Suppose your broker recommended investments with extended lock-up periods or limited liquidity without explaining the risks and impact on your cash flow. In that case, it may be unsuitable, especially if you require access to your funds shortly. Given your investor profile, an unsuitable investment lawyer can evaluate whether the illiquid investment was appropriate for you.
- Complex investment products with unclear risks: Some financial products, such as derivatives, structured products, or certain alternative investments, can be complex and challenging to understand. If your broker recommended these products without explaining the risks involved, it could be considered an unsuitable investment. Brokers need to define the risks and potential returns associated with any investment. Unsuitable investment lawyers can advise whether your broker provided you with adequate notice of the risk associated with an investment.
- Account churning or excessive trading: If your broker excessively trades in your account to generate commissions without regard to your investment goals, it may be a case of account churning. Churning is illegal when a broker engages in excessive trading to generate commissions for themselves, which may result in unnecessary costs and negatively impact your investment performance.
Suppose you suspect that you have been sold unsuitable investments. In that case, you should consult an experienced, unsuitable investment lawyer who can help you assess your legal recourse.
What is my Suitability Profile?
The broker must consider the following before making investment recommendations:
- Age of the Investor—An investor’s age may be an important part of the profile. What may be a suitable investment for a 25-year-old may not be appropriate for someone nearing retirement age. Those approaching retirement may want to contact an unsuitable investment lawyer if their broker recommends an overly aggressive set of investments.
- Investment Objectives – When an investor begins their relationship with a new broker, they will be asked to choose one of the following: Preservation of Capital, Current Income, Growth and Income; Capital Appreciation, and Aggressive Growth. According to FINRA rules, the investment recommendations must follow the investor’s objective. For example, if an investor’s objective was capital preservation, a portfolio of high-risk stocks may be considered unsuitable investments. Any client unsure whether their broker failed to build a portfolio reflecting their investment objectives should contact an unsuitable investment lawyer.
- Other Investments—A broker must understand other investments before recommending an investment. Diversification could protect the investor from market fluctuations. As the adage says, don’t put all of your eggs in one basket.
- Tax Status—Financial advisors must consider the tax implications of any investment before recommending it. For example, some financial professionals may improperly recommend a switch or trade variable annuities to generate a commission. Any investor in such a situation should consider contacting an unsuitable investment lawyer. While variable annuity switching is not illegal, it is often not in the client’s best interest, and it could also have adverse tax consequences. Thus, it could be considered an unsuitable investment.
- Financial Situation and Needs – This refers to the investor’s current and future financial situation, including account assets, such as wealth and income, set off against liabilities, such as debt and dependents.
- Investment Experience—Certain investments, such as high-risk, high-reward investments in unregistered securities, may only suit experienced or sophisticated investors. Unsuitable investment lawyers can investigate a client’s history as an investor to determine whether they have the experience and knowledge to add complex investment products to their portfolio.
- Liquidity Needs—Liquidity is the degree to which an asset or security can be quickly bought or sold fairly. Highly illiquid Investments, such as non-traded REITs or private placement investments, may be unsuitable for investors who plan to retire soon.
- Risk Tolerance—The most critical factor in making investment recommendations, risk tolerance, describes how much an investor can afford to lose. It is a key component of an unsuitable investment lawyer’s case.
Frequently Asked Questions
Brokers have a fiduciary duty to act in their clients’ best interest and must adhere to FINRA’s “suitability rule” (Rule 2111). This rule requires brokers to:
- Understand the client’s financial profile.
- Recommend investments that match the client’s goals and risk tolerance.
- Avoid high-risk investments for clients seeking conservative growth or income.
An investment may be unsuitable if:
- It involves risks the client was unaware of or did not consent to.
- The investment does not match the client’s financial needs, such as liquidity requirements or time horizon.
- It results in excessive losses or costs due to high fees or frequent trading.
Common examples include:
- High-risk investments like penny stocks or leveraged ETFs for conservative investors.
- Illiquid investments, such as private placements or non-traded REITs, for investors needing quick access to funds.
- Over-concentration in a single security, sector, or asset class.
- Recommendations of complex or high-risk securities you do not understand.
- High-pressure sales tactics or frequent trading in your account (churning).
- Losses that are inconsistent with your risk tolerance or financial goals.